SDS Seminar Series – Chad Hazlett, University of California, Los Angeles
Sep
25
2026
Sep
25
2026
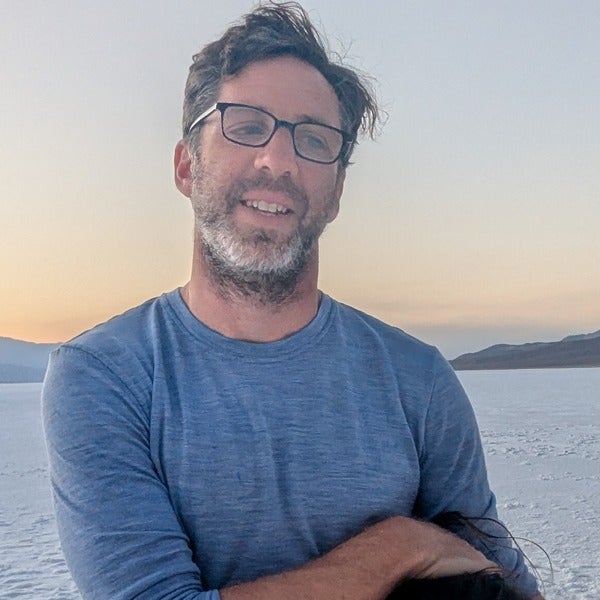
The Fall 2026 SDS Seminar Series continues on September 25th from 2:00 p.m. to 3:00 p.m. with Chad Hazlett (Professor of Political Science and Statistics, UCLA). This event is in-person in the Avaya Room (POB 2.302).
Title: The Synthetic Confounder: What Pre-Treatment Outcomes Can and Cannot Buy in Longitudinal Causal Inference
Abstract: Longitudinal data are attractive for causal inference about the effects of events on the units that experience them, because repeated pre-treatment outcomes seem to let units serve as their own controls and to carry information about confounders that would otherwise go unadjusted. The methods that exploit this intuition place different gambles. Difference-in-differences (DiD) and fixed-effects (FE) approaches use differencing or unit intercept shifts to remove time-invariant confounding; lagged-dependent-variable (LDV) regression and synthetic control (synth) condition on the pre-treatment outcomes to absorb whatever information they carry; and Arellano-Bond instruments with distant lags. Each is unbiased or consistent under its own demanding assumptions. We begin by showing how fragile those assumptions are under two features of the data we cannot typically rule out: past outcomes may be a cause of later outcomes ("autocausation"), and one or more past outcomes may affect the probability of treatment ("feedback"). Together these render DiD, FE, and Arellano-Bond biased and inconsistent even in the total absence of any confounder. LDV and synth survive that case, but fail once a confounder is introduced, even a time-invariant one, recovering slowly as the number of pre-treatment periods grows.
We introduce the synthetic confounder (synthconf) approach, which is consistent under autocausation and feedback whether there is no confounder, a time-invariant confounder, or a time-varying confounder representable as a rank-one signal f(t) interacting with unit-level confounding U_i through a linear factor model. Its core restriction is a "vanishing lag" assumption: the outcome at time t may directly affect outcomes up to t + ν, but not beyond. Consider the precision matrix of the observables augmented with U as though it were observed: entries for pairs of outcomes farther apart than ν must be zero. Marginalising U, the observed precision is a sparse matrix with a known zero pattern minus a rank-one term, and both parts can be recovered by a convex sparse-plus-low-rank fit, from which the treatment effect is read directly. Inference follows by the delta method, with coverage validated in simulation. We then propose a sensitivity analysis that asks how much unadjusted confounding would be needed to alter the conclusion, benchmarked against the confounding strength of the pre-treatment outcomes and of the estimated confounder path f(t).
Other Events in This Series
Nov
13
2026
SDS Seminar Series – Arian Maleki, Columbia University
Accurate and efficient data point removal for high-dimensional settings
2:00 pm – 3:00 pm • In Person
Speaker(s): Arian Maleki